On December 31, 2015, Joshua Chibueze saw a viral post: a woman had broken her kolo, a local wooden savings box, to show what she had saved.
Chibueze’s first thought was his own savings. He saw the post as a fix for his problem and wanted to try it himself. “I wanted to actually save by all means,” he recalled in an interview at the Lagos office of the wealth management company he co-founded, PiggyVest.
He was 23 and, like most of his friends at the time, broke. “How can you go an entire year and you have nothing to show for it?” he said. “You want to buy rice and oil for your parents at the very least.”
He ordered a kolo from an online vendor to start saving himself. On January 1, 2016, he tweeted, “It’s only natural to think about an online solution for this piggybank idea, but then you have to really understand how Nigerians think”. It was the first time the idea went public.
Odun Eweniyi, now PiggyVest’s chief operating officer, replied that it could take the shape of an e-wallet, and the conversation moved offline to the rest of the team.
Somto Ifezue, their friend and PiggyVest’s chief executive officer, bought the domain piggybank.ng and built the first version of a digital kolo within days.
That version let a user link a debit card, pick an amount and a schedule, and PiggyVest debited the card every day, week, or month automatically. Savings stayed locked until the end of each quarter, when the user could withdraw them for free. Early withdrawal cost a 5% fee, and it worked. People who had never managed to leave money in a bank account left it for three months to avoid paying it.
When the product went live in January 2016, Chibueze told the kolo vendor to sign up. He did, becoming PiggyVest’s first customer outside the founding team, and eventually stopped selling boxes.
About 700 people had joined by the end of 2016, roughly 400 of them active users. The following year, PiggyVest built the business model it still runs on today: investing users’ savings, paying them interest from the returns, and keeping a margin.
Today, Chibueze says PiggyVest has about 6.7 million users. The company paid ₦1.3 trillion ($983 million) back to users in 2025 alone and more than ₦3 trillion since 2016, worth at least $2.3 billion at the exchange rates of the years it was paid. Its parent company, Piggytech Global Limited, also owns Pocket, a payments app built on a microfinance bank, along with PiggyVest, a licensed fund manager.
Getting there meant convincing Nigerians to hand their card details to a website run by people in their early twenties, in the year a Ponzi scheme stole billions from Nigerians. It took more than a year of pitching before anyone invested and four years on other companies’ licences.
“We did not have licences in the beginning,” Chibueze said. “We had ourselves.”
The repeat offenders
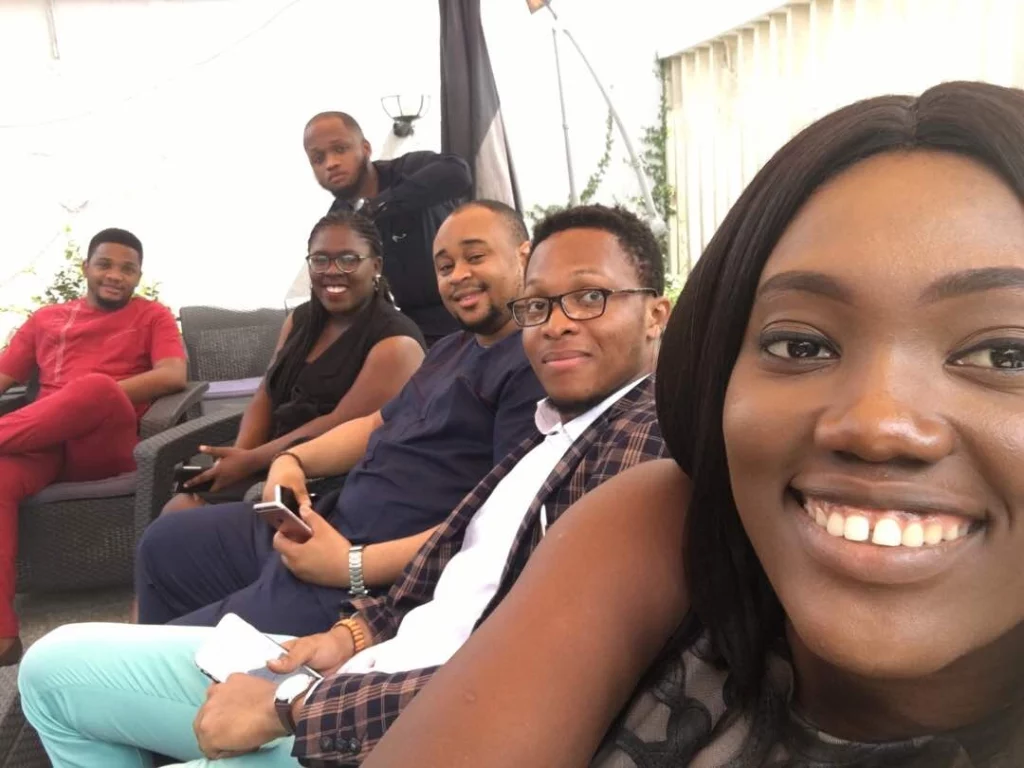
PiggyVest began as a side project for a team whose main business was dying. In late 2015, PushCV, the job platform the founders had run since 2014, had more than a million registered users and was second only to Jobberman in its market, according to Chibueze.
It had also almost run out of money. Running the platform cost more than it earned, and the team could not sell to the businesses whose hiring budgets would have closed the gap.
“We had done a bit of layoffs,” he said. “Barely had five staff left.”
What little income PushCV still earned kept PiggyVest running in the months when no investor would fund it, said Eweniyi. She was 23 in 2016, about six months younger than Chibueze. Ifezue, who is now chief executive, was 25.
PiggyVest was one of many attempts. The team built 99 Staff, which found outsourced workers for companies; 500 Dishes, which let people who cooked at home sell bulk meals and ran two food festivals; Front Desk, which Eweniyi describes as their own version of Shopify; and Household, for booking cleaners. Olumide Soyombo, who would later lead PiggyVest’s seed round, used to call them “repeat offenders,” Eweniyi said.
“We’d been wanting desperately to solve something for this generation,” Eweniyi said in an interview with TechCabal. “We spotted the piggy bank one, and that’s the one that took off.”
PushCV had seven founding members: Ifezue, Eweniyi, Chibueze, Ayo Akinola, Ibukun Akinola, Terry Kanu and Nonso Eagle. All seven still work together.
“Our story is not complete without all seven of us,” Eweniyi said. “The three co-founders of PiggyVest are the three people that you know, but the founding team that did the early work on PiggyVest is the seven of us.”
The seven could build the website, but the product depended on a payment feature that was still new in Nigeria: charging a saver’s card automatically every day, week, or month. Paystack, then a young payments startup, had recently made that possible, and PiggyVest became one of its first customers.
That partnership helped when PiggyVest’s first product went live in January 2016 but came offline almost immediately. The team had to work out with Paystack how scheduled debits would handle the one-time passwords Nigerian cards required and relaunched only once they had. Even then, the technology was not perfect. Some customers were debited four or five times for a single scheduled saving, and a few were charged 11 times.
“It was very stressful,” Eweniyi said.
The founders answered complaints by email, while one of them worked with Paystack on a fix. PiggyVest then stopped charging a card again until Paystack had reported back on the previous charge.
Chibueze compares the relationship to Stripe and Shopify’s early partnership, when a demanding customer helped a payments company refine its product as both businesses grew.
“I think we were one of those customers for Paystack,” he said.
The hard problem
The harder problem for the early PiggyVest team to solve was trust. MMM, a Ponzi scheme, had drawn in about 3 million Nigerians when it froze withdrawals on December 13, 2016. The Nigeria Deposit Insurance Corporation later put participants’ losses at ₦18 billion (about $71 million at 2016’s average rate).
“We were dealing with, ‘Oh my God, you guys are going to be the next MMM,'” Chibueze recalled. At the time, Piggyvest had no app or licence, only a website.
The founders deliberately put their own faces on the brand. Many early users were the founders’ age, Chibueze said, and started small. A saver would deposit ₦10,000 (about $40 at 2016 rates), withdraw it at the end of the savings period, then return with ₦20,000 (about $80). Eweniyi said most of the first 700 users knew the team from PushCV or one of their earlier products and referred others.
On December 31, 2016, as the first savers were withdrawing their money, Osikhena “Osi Suave” Dirisu tweeted that he had been using the platform. Dirisu was a presenter on The Beat 99.9 FM, a popular music radio station in Lagos.
The tweet went viral, and Eweniyi said it was the moment the founders knew they had something.
“The trust really comes from the fact that they give you their money,” Chibueze said. “And when they want it, you give it back.”
Fifteen months to the first cheque
PiggyVest was born into Nigeria’s first full-year recession since 1987, after the Central Bank of Nigeria stopped defending the naira’s peg of about ₦199 to the dollar, and the currency fell to nearly ₦300 in June 2016.
Eweniyi said the crash barely registered inside the company. “We didn’t even have a revenue model in 2016. We were just building,” she said.
PiggyVest started out paying users high interest, she said. When the market turned, the team had to learn quickly how interest rates behaved and how to pass returns on to users, and that work did not begin until about February 2017.
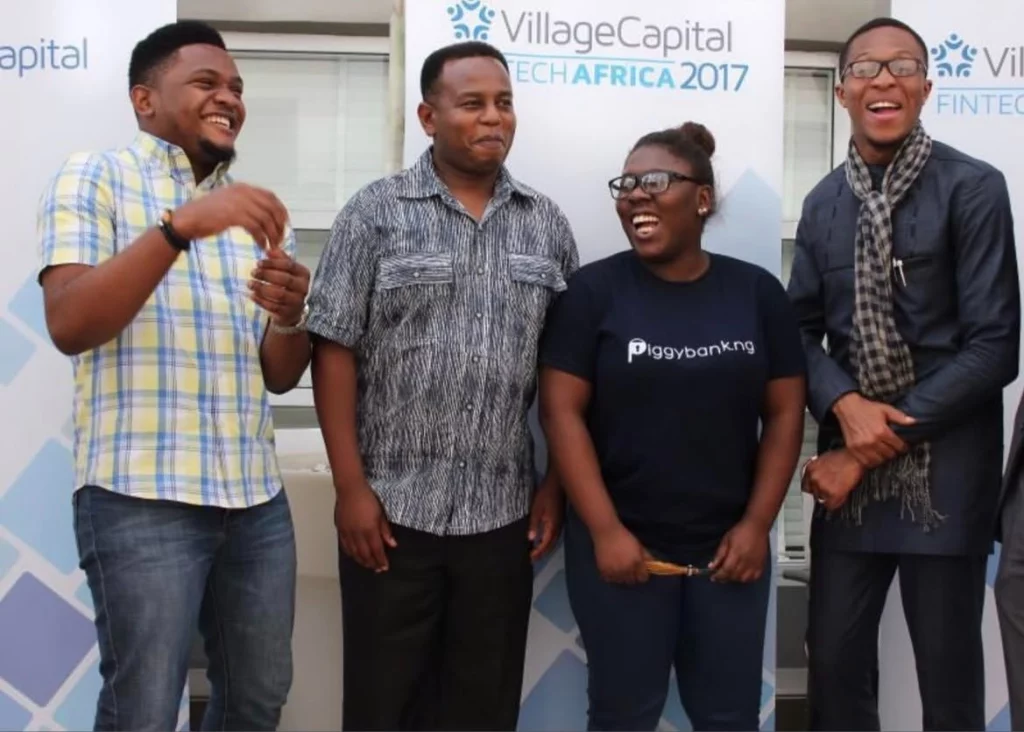
Investors were harder to convince than users. The founders pitched from January 2016 until April 2017, when Village Capital, a US investor that runs programmes for early-stage companies, wrote PiggyVest’s first cheque: $50,000.
“The case against was the obvious one for that stage and geography: an unproven regulatory path for holding consumer savings, thin early revenue, and a category where trust is everything and it takes years to earn,” Village Capital said in a written response to TechCabal.
“We made the bet that the team’s grasp of the customer would compound faster than those risks,” the statement added.
By 2018, PiggyVest had about 53,000 customers. Users saved about ₦700 million (roughly $2.3 million) on PiggyVest in 2017 and ₦4.5 billion (roughly $14.7 million) in 2018, according to Chibueze. In January 2019 alone, they saved ₦1 billion (roughly $3.3 million).
In May 2018, the company announced a $1.1 million seed round. LeadPath Nigeria, the angel investment firm founded by Olumide Soyombo, committed $1 million, and Village Capital and Ventures Platform put in $50,000 each, with Soyombo joining PiggyVest’s board. Chibueze said the funding was a mix of equity and debt agreed after a meeting at Google Launchpad, where the founders presented no documents.
“They just asked us for our story,” he said. “Then they gave us the money.”
That round is the only one PiggyVest has announced. VFD Group, the Nigerian investment holding company, took a 12% stake in 2021, and Flutterwave invested about $3 million in mid-2023 through a simple agreement for future equity. PiggyVest told TechCabal in February 2024 that it had raised about $5 million in total since 2016.
For comparison, Flutterwave, founded the same year, has raised almost $500 million.
Borrowed licences and scaling into a crisis
For its first four years, PiggyVest held users’ money through partners. It worked with microfinance banks, a commercial bank and an asset management company that held its funds, Chibueze said. Every partner took a share of the returns.
“Let’s say you’re supposed to make 5%; you make only 2% or 3%,” he said. “So it reduces the interest you can pay your customers.”
PiggyVest could not afford its own licences until, around the 2020 lockdown, it grew too big to keep partnering, Eweniyi said. “It was a damn relief,” she said. “We could come out boldface in front of our regulators: this is us, this is what we do. We’re not hiding behind a partner.”
In 2019, the Central Bank of Nigeria (CBN) made clear that only a licenced bank could call itself one, Chibueze said. Nigerian banking law reserves the word for licenced banks. Piggybank.ng became PiggyVest. Chibueze describes it as one of the two hardest moments of the decade.
“Selling that story without people feeling like we’re about to shut down was difficult,” he said.
He was also the founder who resisted it. Eweniyi said there were maybe 48 hours of back-and-forth before they agreed on a new name and he came around. “He was like, ‘No, we don’t have to do this,'” she recalled. “I couldn’t see what he was seeing at the time.”
PiggyVest was still a small company when it changed its name. When the COVID-19 lockdown began about a year later, it had fewer than 30 staff, and Eweniyi personally ran hiring, treasury, human resources, parts of finance, compliance, risk and, for a time, content and social media.
“I did the Excel sheets myself at the start,” she said of treasury. Then users began signing up faster than the team could hire, and 2021 became, in her words, “a big adjustment period.” By the end of that year, she handed over hiring to the company’s head of people.
The first major test of this new scale came on a Sunday in 2021. On February 7, Providus Bank, a small Nigerian commercial bank, deactivated the virtual account numbers PiggyVest, Cowrywise, its biggest competitor, and other fintechs used to receive deposits.
Providus said it was reviewing the service in line with new regulations two days after the CBN ordered banks to stop facilitating cryptocurrency transactions. Money users had already sent to those account numbers stopped showing up in their PiggyVest wallets.
Eweniyi said her annoyance about it lasted about 15 minutes. The founders quickly gathered at Ifezue’s house and agreed to say nothing in public until they had a fix. It helped that they all lived close to each other. They still do.
Flutterwave provided replacement account numbers from Wema Bank, a mid-size Nigerian bank, and around 4 p.m. PiggyVest announced the problem and the solution. Clearing the stuck deposits took weeks, Chibueze said.
The lesson stayed with the company. In 2025, PiggyVest retired the virtual account numbers it had relied on since its early years and moved deposits onto its own payment system, run by Pocket.
The second test of 2021 was the one Eweniyi calls the closest PiggyVest came to failing. In October, Imagine Global Solution, an investment company, collapsed amid fraud allegations, and social media posts claimed PiggyVest had lost ₦2 billion (about $5 million at 2021’s average rate) to it. PiggyVest said in a statement that no user funds had suffered any loss.
Eweniyi said the news “just came out of nowhere” and that its collapse “created a second-order effect that led to many withdrawals on PiggyVest.”
For the first five hours, she said, her heart would not stop racing, and she cried. She called an older friend who had worked in banking, followed his advice on surviving a run of withdrawals to the letter, and within a week “it was almost like it never happened.”
A separate app for spending
PiggyVest has kept one rule since 2016: money that goes in is meant to stay. When the founders became curious about how users spend, they built that outside the savings app.
“PiggyVest was never going to be a product that housed spending,” Eweniyi said. “We can’t put spending inside of a savings and investment app.”
The spending product was Abeg, a peer-to-peer payments app launched in September 2020. In April 2021, with about 20,000 users, Abeg became the headline sponsor of the sixth season of Big Brother Naija, the reality TV show. Piggytech formally took a 99.9% stake in Abeg Technologies that November.
Eweniyi said the logic was a chicken-and-egg problem. A payments app needs shoppers and merchants, and the fastest way to get shoppers was through a show the country was glued to during lockdown. By June 2022, Abeg had about two million users. It received approval in principle for a mobile money licence from the CBN in April 2022 and rebranded as Pocket.
Asked whether the bet paid off, Eweniyi said, “Yes and no.” The sponsorship did what it was meant to do, but the product was the wrong version of itself. “I wish we’d put a bit more thought into that product before going on that platform,” she said.
Chibueze said Pocket is now profitable on its own and processes all of PiggyVest’s transfers.
Slow on purpose, then faster
PiggyVest never had the option of speed. Money came slowly, so the founders built slowly, proved their unit economics, and treated assets under management as the one number that mattered.
“There is a speed that I think the class of 2021 and 2022 startups had that I don’t think we from 2015 and 2016 had the luxury of having,” Eweniyi said.
The slow money had a cost, and both founders said so. “If you ask me, we should have been further,” Chibueze said. Eweniyi agreed, with a caveat. “Maybe we would have moved faster and quicker with more money. But would we have moved better? I don’t know.”
She also credits luck: Chibueze seeing the kolo post, Paystack launching recurring payments when it did, and a young, newly connected population ready to try something that started as a digitised wooden box.
Village Capital, which wrote the first cheque nine years ago, credits the founders. “A cheque at the right moment can buy the two things a young company cannot manufacture on its own: conviction from an outside party when few others are looking and the room to keep going long enough to prove the idea,” it said in its response to TechCabal. “Early capital does not build the product, earn the trust, or hold a team together through the hard years. The founders do that.”
PiggyVest is rebuilding its app from the ground up for the first time since 2023, and Eweniyi wants the company to become the digital financial ecosystem for every Nigerian, at home and abroad, and eventually for Africans.
“We’ve executed very intentionally for 10 years,” she said. “Now I want to execute faster for the next 10.”