A surge in cybercrime across African banks and fintechs is forcing financial institutions to retreat to domestic markets, stalling cross-border integration and leaving continental initiatives like PAPSS and AfCFTA underutilised.
An escalating wave of digital fraud has emerged as the primary operational deterrent to cross-border financial integration in Africa, with 88% of commercial banks and fintech companies reporting increased electronic financial crimes.
The finding, detailed in the sixth edition of the African Financial Industry Barometer presented at the Africa Financial Industry Summit (AFIS) in Luanda, highlights a growing security crisis that is prompting lenders to abandon cross-border ambitions in favour of domestic retrenchment.
Published jointly by Deloitte and Jeune Afrique Media Group, the survey gathered responses from financial leaders across 20 African nations.
Although overall industry confidence remained steady at 8 out of 10, matching the previous year’s rating, operational caution has intensified significantly as institutions struggle to secure digital channels against cross-border fraud.
TC DATA LAB / AFIS 2026Africa is confident in its financial future. So why is integration stalling?
Financial institutions rate the industry’s outlook highly, yet many are consolidating at home, regional initiatives are struggling to deliver, and digital fraud is rising. Explore the contradiction in the 2026 African Financial Industry Barometer.
20 African countries AFIS–Deloitte survey 2026 findings 01 The optimism 02 The reality 03 The obstacles 01 / THE OPTIMISMConfidence is high. Expansion is another matter.
African financial leaders remain broadly optimistic. But confidence varies significantly between institutions already operating across borders and those focused on domestic markets.
Overall industry confidence 8/10 Unchanged from the previous year, despite mounting operational and integration challenges. Confidence depends on where you operate Capital markets 8.57 Multi-country institutions 8.53 Regional financial groups 8.00 Insurance companies 7.45 Domestic institutions 7.33Scores are out of 10. The categories include both institution types and business segments; they are not mutually exclusive groups.
Where do institutions want to grow?Select a strategy to see what the survey says about expansion priorities.
Domestic consolidation 49% Regional partnerships 42% Organic regional expansion 37% Cross-border M&A 32% Nearly half are focused on home markets.Domestic consolidation was the most commonly identified growth strategy, particularly among banks and insurance companies.
Partnerships offer a less capital-intensive route.Some local institutions favour regional alliances instead of establishing wholly owned operations abroad.
Fintechs are more expansion-oriented.Fintech operators are the group most inclined towards organic regional expansion, despite their exposure to digital fraud.
Established pan-African groups are selective buyers.Multi-market financial groups continue to consider acquisitions to strengthen existing regional footprints.
These percentages represent reported strategy preferences and are not parts of a single whole. Separately, 25% reported no regional expansion plans.
02 / THE REALITYThree integration projects. Limited tangible progress.
AfCFTA, PAPSS and the African Exchanges Linkage Project are intended to make cross-border commerce, payments and investment easier. Survey respondents see slow implementation. Select a project to compare the findings.
AfCFTA Trade integration PAPSS Cross-border payments AELP Capital markets AfCFTAAfrican Continental Free Trade Area — designed to deepen intra-African trade and regional economic integration.
HOW RESPONDENTS ASSESS IMPLEMENTATION 7% Tangible progress 69% Too slow 24% StalledWhat stands out: Only 7% report tangible progress, despite the agreement’s continent-wide ambition.
PAPSSPan-African Payment and Settlement System — designed to support intra-African cross-border payments in local currencies.
HOW RESPONDENTS ASSESS IMPLEMENTATION 19% Tangible progress 57% Too slow 24% StalledWhat stands out: PAPSS has the highest reported tangible progress of these three projects, but institutional participation remains limited.
The PAPSS participation problemBeyond perceptions of progress, the survey asked institutions about their connection plans.
11% Already connected 12% Currently onboarding 45% No plans to connectThese are selected response categories, not a complete breakdown of all respondents.
AELPAfrican Exchanges Linkage Project — intended to connect participating African stock exchanges and facilitate cross-border investment.
HOW RESPONDENTS ASSESS IMPLEMENTATION 4% Tangible progress 53% Too slow 43% StalledWhat stands out: AELP records the weakest progress assessment. Separately, 56% of respondents report no concrete benefits from the project.
03 / THE OBSTACLESThe risks behind the retreat
Digital fraud is rising, cybersecurity remains a major concern, and the infrastructure needed to deploy defensive AI tools is uneven. Select a risk category to explore the findings.
Digital fraud Reported increase Cybersecurity Operational concern AI barriers Defensive technology Digital fraud is increasingShare of surveyed institutions reporting an increase in digital fraud.
88% Banks and fintechs reporting increased digital fraud 66% All surveyed institutions reporting increased digital fraudThe tension: Fintechs are among the institutions pursuing regional expansion, yet banks and fintechs also report particularly widespread increases in digital fraud.
Cybersecurity tops the risk agendaShare identifying cybersecurity as a major operational concern. This is distinct from reporting an increase in digital fraud.
Commercial banks 79% Fintechs 63% All surveyed institutions 51%Why this matters: Cross-border activity introduces additional operational and counterparty complexities, making security capacity especially important.
AI could help detect fraud. Deployment is harder.85% recognise the impact of AI for fraud detection, but institutions report significant barriers to implementation.
Data quality 56% Cybersecurity and data privacy 56% Technical skills 44% Regulatory uncertainty 33% Lack of clear commercial case 15%The contradiction: Institutions recognise AI’s potential, but data, security and talent constraints complicate its practical deployment.
THE BIG PICTUREConfidence in Africa’s financial future is not the same as confidence in operating across its borders. The survey reveals a gap between industry optimism, actual integration progress and the operational capacity needed to connect African markets.
How to read this dataSource: Sixth African Financial Industry Barometer, presented at AFIS 2026 by Deloitte and Jeune Afrique Media Group. The survey gathered responses from financial leaders across 20 African countries.
Confidence: Scores use a 0–10 scale. Institution categories and business segments can overlap.
Growth strategies: Respondents could identify different approaches. Percentages should not be added together.
Integration: AfCFTA, PAPSS and AELP percentages reflect surveyed institutions’ assessments of progress. They are not independent measurements of actual transaction volumes, trade flows or market connectivity.
PAPSS participation: The connected, onboarding and no-plans figures are selected categories, not a complete distribution.
Risks: Increased digital fraud, cybersecurity concerns and AI adoption barriers are different survey measures. They should not be interpreted as equivalent or as proof that fraud alone caused institutions to avoid regional expansion.
Data: AFIS–Deloitte, Sixth African Financial Industry Barometer (2026 preliminary findings).
Coverage: Financial industry leaders across 20 African countries.
Visualisation and analysis: TechCabal Data Lab.
Domestic consolidation over cross-border expansion
Rather than deploying capital into regional corridors, financial institutions are prioritising their domestic bases.
When asked about growth strategies, 49% of respondents identified consolidating their existing national markets as their primary objective.
Regional partnerships and alliances followed at 42%, while only 37% favoured organic expansion into other African jurisdictions. Formal cross-border mergers and acquisitions registered 32%, and a quarter of all surveyed institutions stated they have no plans for regional expansion.
Strategic postures reflect distinct operational priorities across sectors. Commercial banks and insurance companies are focusing almost exclusively on domestic consolidation, seeking to avoid unfamiliar legal and counterpart risks abroad.
Fintech operators represent the primary group pursuing organic regional expansion, even as they face the highest incidence of digital fraud. Pan-African banking conglomerates continue to pursue selective acquisitions to defend their established multi-market footprints, while purely local institutions favour bilateral partnerships as a low-capital route beyond their domestic borders.
This divergence in strategy is mirrored in institutional sentiment. Multi-country institutions reported confidence scores of 8.53 out of 10, and regional banking groups gained 0.75 points to reach 8.00.
Capital markets registered the sharpest rise in optimism, increasing from 6.50 to 8.57. Conversely, purely domestic institutions saw their confidence drop to 7.33, while the insurance sector declined by 0.90 points to 7.45.
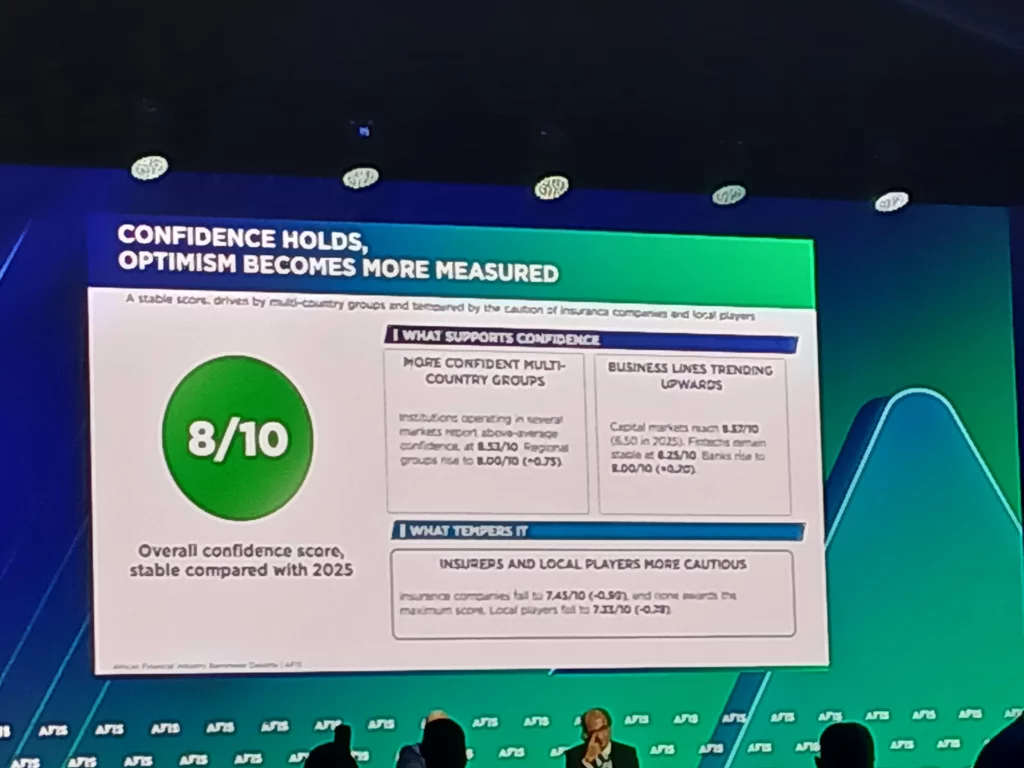
José Barata, Managing Partner and Banking Sector Lead at Deloitte Angola, noted during the presentation that institutional scale heavily dictates market sentiment.
Barata explained that while confidence remains high among multinational and regional groups with established structures, purely local and national players report lower confidence, indicating that capital allocation decisions require a closer assessment of specific institutions and their operating environments.
Flagship integration projects face an adoption stall
The inward turn of the financial sector is taking a visible toll on continental integration initiatives, including the African Continental Free Trade Area (AfCFTA), the Pan-African Payment and Settlement System (PAPSS), and the African Exchanges Linkage Project (AELP).
Only 7% of respondents reported tangible commercial progress resulting from AfCFTA, with 69% stating that implementation is moving too slowly, and another 24% viewing the agreement as stalled.
The AELP, designed to interconnect stock exchanges across the continent to unlock regional portfolio investments, recorded even weaker sentiment.
Just 4% of respondents reported tangible progress from the linkage project, while 53% described its pace as too slow and 43% considered it at a complete standstill. Fifty-six per cent of respondents reported experiencing no concrete benefits from the platform.
Adoption metrics for PAPSS, the African Union-backed payment network developed to clear intra-African trade in domestic currencies, indicate severe structural friction.
Although 19% of institutions acknowledged tangible operational progress, 57% stated that rollout has been too slow, and 24% considered it stalled.
More critically, 45% of surveyed institutions reported having no plans to connect to PAPSS. Only 11% are actively connected, with an additional 12% currently working through onboarding.
Across the wider survey, 41% of respondents reported deriving no commercial benefits from either AfCFTA or PAPSS.
Lenders attribute this hesitation to unmitigated counterparty liabilities, clearing uncertainties, and an absence of harmonised dispute-resolution systems.
In the absence of regulatory alignment across jurisdictions, cross-border operations must comply with competing anti-money-laundering, customer verification, and capital repatriation rules, thereby driving up administrative costs.
Barata stressed that software and infrastructure cannot bridge this gap without systemic alignment, observing that regional integration requires more than a stated intention to operate across borders.
He emphasised the necessity of interconnected payment networks, practical settlement protocols, stronger regulatory cooperation, and the foundational financial mechanisms required to process cross-border transactions safely.
The $775 billion capital mobilisation gap
The operational retreat is compounding the continent’s internal capital mobilisation shortfall. Citing OECD figures from the African Financial Markets Initiative, the report highlights that African pension funds and insurance firms hold an estimated $775 billion in institutional assets. However, this pool of domestic savings remains largely disconnected from long-term real-economy requirements.
While 64% of respondents are actively engaged in financing small and medium-sized enterprises, 41% reported no involvement in funding affordable housing developments.
TC DATA LAB / AFIS 2026Africa has $775 billion in institutional assets. Why isn’t more reaching the real economy?
Africa’s pension funds and insurers hold an estimated $775 billion in assets. But financing for businesses, housing and infrastructure remains constrained. Explore the gap between available institutional capital and its deployment.
Institutional capital AFIS 2026 Interactive explainer ESTIMATED AFRICAN PENSION AND INSURANCE ASSETS $775bnThis is an estimated stock of institutional assets — not cash sitting idle, and not an amount that could immediately be redirected into new projects.
THE CENTRAL QUESTIONHow can more long-term African savings support productive investment without undermining pension obligations, insurance liabilities or investment risk standards?
01 The capital 02 The financing gap 03 What could change? 01 / THE CAPITALThe money exists. But it isn’t a single pot.
The $775 billion estimate brings together long-term assets managed by pension and insurance institutions. These investors have different obligations, liquidity needs and investment mandates. Select a category to understand why that matters.
What does $775 billion actually mean?It describes an estimated asset pool managed by institutions across Africa. The survey does not provide a verified allocation of this total between pensions, insurers, infrastructure, SMEs and housing.
Pension funds Long-term obligations Insurers Liability matching The combined pool $775bn estimate Pension capital is long-term, but not unrestricted.Pension funds invest to meet future retirement obligations. Infrastructure and other long-duration assets may fit some portfolios, but investments must satisfy rules on risk, diversification, liquidity and expected returns.
Insurers invest against future claims.Insurance portfolios must support claims-paying capacity and regulatory capital requirements. Their investment choices depend on the duration and predictability of liabilities, as well as the risk and liquidity of available assets.
The combined pool is not an investment budget.The $775 billion estimate demonstrates the scale of institutional assets. It does not tell us how much is uncommitted, how much is invested outside Africa, or what proportion could safely finance additional domestic and regional projects.
02 / THE FINANCING GAPFinancial institutions are not equally engaged.
The survey reveals a difference between financial institutions’ participation in SME financing and affordable housing. These figures measure institutional engagement, not the share of the $775 billion allocated to either sector.
Institutions significantly engaged in SME financing 64%Indicates reported institutional engagement, not the volume of SME credit.
Institutions with no affordable-housing financing engagement 41%Measures non-participation, not the size of the housing finance deficit.
Explore the two financing marketsSelect a sector to see why institutional participation does not automatically translate into sufficient financing.
SME financing Affordable housing 64% report significant SME financing engagement.That indicates substantial institutional activity, but it does not reveal how much finance SMEs receive, the terms on which it is offered, or how much unmet demand remains. Lending risk, information gaps and the availability of suitable financing instruments can constrain access.
41% report no affordable-housing engagement.Housing finance can require long-duration funding and reliable repayment structures. Land administration, project preparation, affordability and credit risk can affect investment viability. The survey’s non-participation figure does not quantify the funding shortfall.
03 / WHAT COULD CHANGE?Three ways to make long-term capital more investable
Mobilising institutional assets is not simply a matter of directing funds towards new sectors. Investors need suitable instruments, manageable risks and confidence in how projects are governed. Explore three possible approaches.
01 Deepen capital markets 02 Share investment risk 03 Improve governance INVESTMENT INSTRUMENTS Give institutions more suitable assets to buyDeeper bond markets, investment funds, securitisation structures and infrastructure securities could create more investable opportunities for pension funds and insurers.
The goal is not to force capital into particular projects, but to develop instruments whose risk, maturity, liquidity and returns are compatible with institutional mandates.
RISK MANAGEMENT Make viable projects less risky to financeCredit guarantees, first-loss capital, blended-finance structures and development-finance participation can sometimes reduce the risks borne by private investors.
Such mechanisms still have costs and require careful design. They cannot turn fundamentally unviable projects into sustainable investments.
INSTITUTIONAL CONFIDENCE Strengthen the foundations of investmentReliable financial reporting, transparent procurement, enforceable contracts and credible project governance can improve investors’ ability to assess and manage long-term risks.
Better project preparation and regulatory clarity may help expand the pipeline of opportunities that meet institutional investment standards.
These are potential policy and market mechanisms, not quantified forecasts of how much of the $775 billion they could mobilise.
THE CAPITAL PARADOXHaving a large pool of institutional assets does not mean having an equally large pool of capital available for new investment. Mobilising more of Africa’s long-term savings requires bankable projects, suitable financial instruments and credible safeguards for investors.
About the data and what it does not showSource: Sixth African Financial Industry Barometer, AFIS–Deloitte 2026. The survey includes financial institutions across 20 African countries.
Institutional assets: The $775 billion figure is an estimated combined stock of pension and insurance assets. It is not a measure of idle funds or immediately investable capital.
SME financing: The 64% figure represents institutions reporting significant engagement in SME financing. It is not the percentage of institutional assets allocated to SMEs.
Affordable housing: The 41% figure represents institutions reporting no engagement in affordable-housing financing. It is not the proportion of unmet housing-finance demand.
Limitations: The available findings do not quantify how the $775 billion is divided among asset classes, how much is invested abroad, or how much could be redirected into new projects.
Policy options: The final panel describes possible mechanisms for mobilising investment. These are explanatory approaches, not measured outcomes from the survey.
Data: AFIS–Deloitte, Sixth African Financial Industry Barometer, 2026.
Visualisation and analysis: TechCabal Data Lab.
Note: Percentages describe survey responses; they do not represent the allocation of the $775 billion asset estimate.
An executive quoted in the barometer observed that Africa does not lack savings but rather lacks sufficient mechanisms to channel them into productive investments at scale.
Barata reinforced this assessment, stating that the primary challenge is not a shortage of capital, but the absence of functional channels through which funds can be directed toward productive enterprise.
He noted that policymakers and institutions must address investment risk, deepen local markets, and build the confidence required to deploy domestic capital into the productive economy.
To unlock this capital, executives surveyed by Deloitte and AFIS recommended three interventions: opening national markets to reciprocal capital flows, mitigating investment risk through guarantees and blended-finance vehicles, and enhancing corporate governance alongside transparent financial reporting.
The report notes that these measures are interdependent and argues that opening markets without mitigating underlying financial risks will fail to attract institutional investors.
Escalating fraud and an acute talent deficit
The worsening operational risk profile presents an immediate obstacle to these reforms. Cybersecurity now ranks as the primary operational threat for 51% of surveyed institutions, rising to 79% among commercial banks and 63% among fintech firms.
Digital fraud was reported to have increased across 66% of the general industry, escalating to 88% among banks and fintech operators.
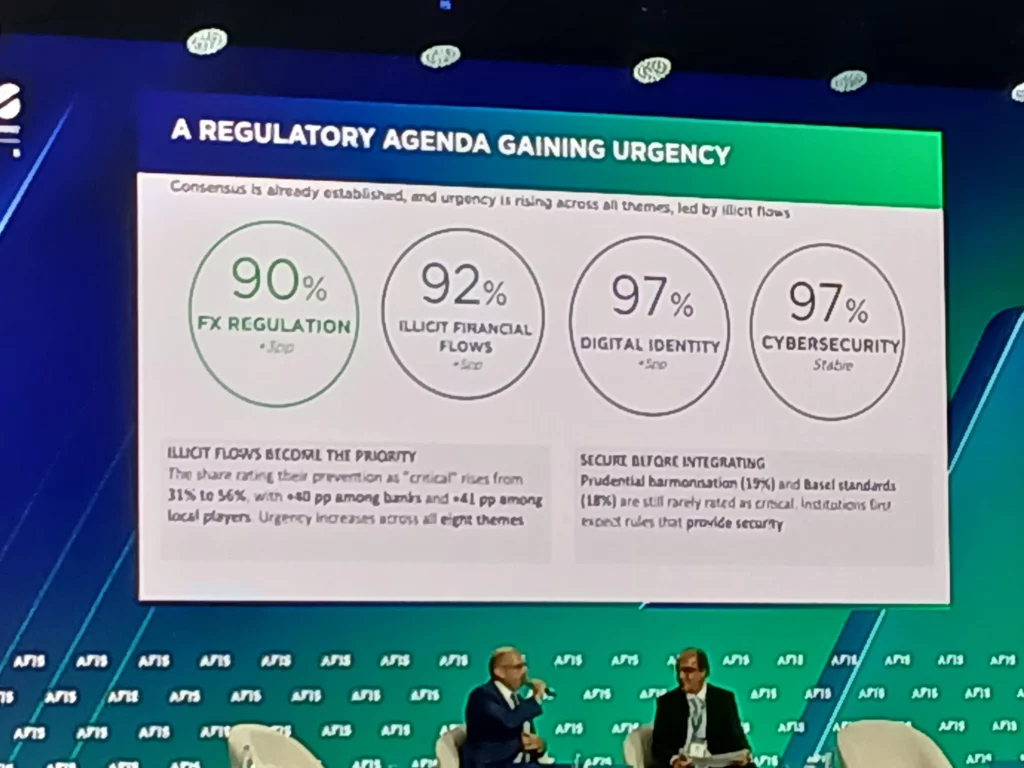
Barata pointed out a contradiction in how institutions perceive this operational environment. He explained that while approximately two-thirds of institutions surveyed previously identified digital fraud as a substantial risk, many continue to perceive their individual exposure as relatively low.
He warned that as digital service delivery expands, exposure to fraud and cyberattacks increases concurrently.
This security exposure is intensified by a widening skills deficit, with 41% of institutions identifying technical talent shortages as a critical risk, an 11-percentage-point increase year-on-year.
External variables have added to the pressure, with 48% of leaders citing geopolitical instability as an operational risk, up six percentage points, and 41% reporting sustained margin compression due to domestic inflation and currency depreciation.
AI ambitions constrained by infrastructure deficits
To counter rising fraud volumes and streamline verification tasks, financial institutions are turning to artificial intelligence.
Practical interest is concentrated heavily in defensive applications, led by fraud detection at 85% impact recognition, process optimisation at 84%, predictive analytics and business intelligence at 74%, and product personalisation at 69%.
Overall, six of the seven AI use cases evaluated in the survey registered impact recognition above 60%, with only 15% of executives citing the lack of a clear commercial case as an adoption barrier.
The challenge instead lies in institutional infrastructure. Deficiencies in data quality were cited by 56% of respondents as a barrier to AI deployment, matching the 56% who cited cybersecurity and data privacy concerns.
Technical skill deficits were identified by 44%, and regulatory uncertainty was noted by 33%. Barata remarked that the sector has shifted from experimental applications to execution, with executives focused on deploying automated tools in practice to improve credit underwriting, secure operations, and demonstrate operational returns.
The complete AFIS-Deloitte African Financial Industry Barometer is scheduled for full publication between late January and February.
The preliminary findings suggest that waiting for universal regulatory alignment across all 54 African nations is impractical.
The report recommends pursuing practical gains through bilateral regulatory corridors, institutional capacity enhancements, and sector-targeted frameworks, highlighting the insurance industry as an accessible starting point for cross-border alignment.
The underlying requirement for meaningful integration remains operational security. Until national regulators, central banks, and financial institutions build the technical frameworks necessary to curb the surge in cross-border fraud, the continent’s $775 billion in institutional capital reserves will remain confined within domestic borders.